The Logistics Engine of Southern California
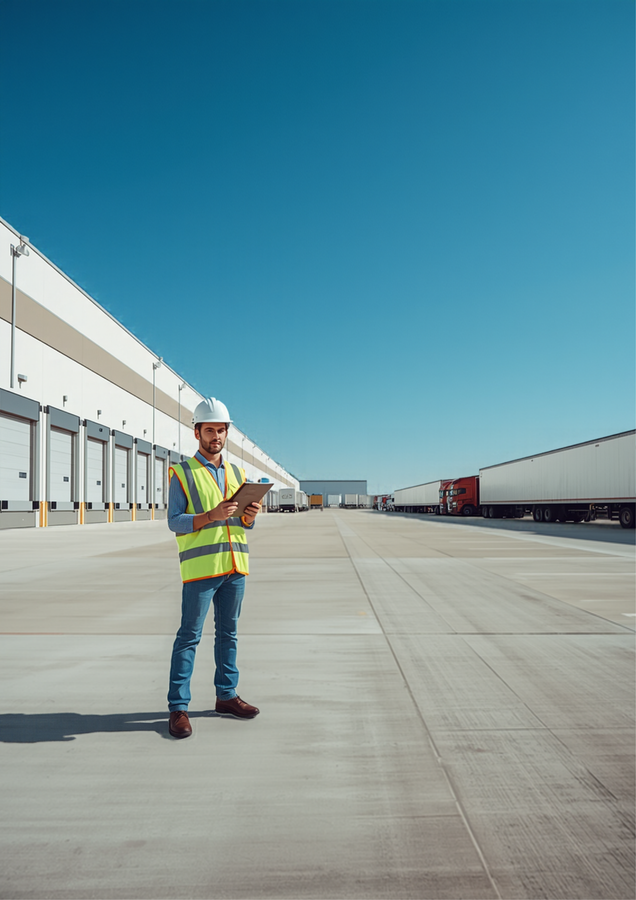
The Inland Empire — spanning Riverside and San Bernardino counties — has become one of the most important logistics and distribution regions in the entire country. Warehouses stretch for miles along the 10, 15, 60, and 215 freeway corridors, moving goods in and out of the ports of Los Angeles and Long Beach to the rest of the nation. But the region is far more than warehouses. Fast-growing residential communities support a dense layer of restaurants, medical offices, retail, and personal service businesses. Construction and trades firms stay busy with the region's continued development. And a meaningful agricultural base persists in pockets throughout both counties. The Inland Empire Chamber of Commerce is a useful resource for owners navigating this regional economy.
For business owners here, that combination creates a genuinely regional risk profile that's different from coastal California. Warehousing and logistics businesses carry heavy commercial auto, workers' compensation, and property exposure tied to large facilities and valuable inventory. Construction and trades businesses carry liability and bonding needs tied to constant new development. And the service businesses supporting all of this growth — restaurants, medical offices, salons, retailers — need the same solid general liability and property foundation that any California small business needs, just scaled to a fast-growing regional market, which is how Barua Insurance approaches coverage here.
General Liability and Property Coverage for a Fast-Growing Region
General liability insurance is the starting point for virtually every Inland Empire business, covering third-party injury, property damage, and similar claims that any business can face regardless of industry. Commercial property coverage protects the physical assets — and across the Inland Empire, that needs to reflect real regional risk factors including wildfire exposure in foothill and canyon areas, extreme summer heat that can strain equipment and HVAC systems, and the sheer scale of inventory sitting inside large distribution facilities at any given time.
For logistics and warehouse operators specifically, getting property and inventory values right is critical, since a single fire, theft, or water damage event in a large facility can represent a loss far exceeding what a standard policy might assume. Smaller Inland Empire businesses — restaurants, retailers, professional offices — often find a business owner's policy to be the most efficient way to combine general liability and property coverage.
Workers' Compensation and Commercial Auto Across the Logistics Corridor
California requires workers' compensation coverage the moment a business has a single employee, and the Inland Empire's concentration of warehousing, trucking, construction, and agricultural work makes this one of the most important coverage lines in the region. Physical injury risk in these industries tends to run above average, and the California Department of Industrial Relations publishes detailed guidance on employer classification and compliance that's worth reviewing directly for any business in transportation or warehousing.
Commercial auto coverage is just as essential given how much of the regional economy depends on moving goods by truck and van across a sprawling freeway network. Fleet operators, independent contractors, and service businesses covering the Inland Empire's wide geography all need commercial auto coverage sized to actual vehicle use, since personal auto policies generally exclude business use and leave real gaps in a work-related accident.
Specialty Coverage: Contractors, Warehousing, and Professional Services
The Inland Empire's constant pace of residential and commercial construction keeps local contractors in steady demand, and many need a contractor's bond to bid on larger projects, along with tools and equipment coverage protecting gear that moves between job sites throughout the region.
Warehousing and distribution businesses should look closely at how their general liability and property policies handle third-party cargo, equipment breakdown, and business interruption — a short shutdown at a major distribution facility can be costly well beyond the direct property damage itself. Professional service firms serving the region's growing population — medical offices, consultants, accountants — should carry professional liability (errors and omissions) coverage, since general liability doesn't respond to claims about the quality of professional advice or services.
Cyber liability coverage has become a practical necessity across nearly every Inland Empire business type, from logistics companies managing shipment data to retailers and medical offices handling customer information. And restaurants and venues serving alcohol need liquor liability coverage, since that exposure is typically excluded from a standard policy. Owners pulling permits can check CalGold, and the California Department of Insurance and SBA's business insurance guide are both useful references.
Coverage Built for a Regional, Not Just a Local, Business
Many Inland Empire businesses operate across multiple cities within the region rather than staying confined to one — a contractor working jobs in Riverside, Upland, and Lake Elsinore, or a logistics company serving facilities throughout both counties. That regional footprint makes it even more important to work with coverage sized to the actual scope of operations rather than a single-location assumption.
Owners who want to map out their own coverage before a conversation can work through our business insurance questionnaire, which covers general liability, a business owner's policy, workers' compensation, commercial auto, professional liability, cyber liability, umbrella coverage, and contractor's bonds. It's worth reading our city-specific guides for Riverside business insurance and Upland business insurance as well, since local factors can still shift the right coverage mix even within the broader region, along with our renters insurance for Riverside tenants guide and our port-to-warehouse comparison with Long Beach business insurance. Our Knowledge Center has more coverage guides for business owners across the region.
To talk through coverage for a business operating anywhere in the Inland Empire, request a quote or call Barua Insurance at (562) 273-3989. We're licensed under California license #6003484 and regularly work with business owners across Riverside and San Bernardino counties.